
Mattress Financing Bad Credit Options That Work

A shopper in Norwich replaces a lot of things on a schedule. A mattress usually isn't one of them. It gets replaced when the sagging starts hurting shoulders, when a guest bed becomes the everyday bed, or when poor sleep starts affecting work and patience at home.
That's why mattress financing bad credit feels so frustrating. The need is real, the budget is tight, and the financing screen can make a basic household purchase feel like a credit exam. For many households in Eastern CT, the smartest move isn't chasing the lowest monthly number. It's figuring out which financing path gives a fair approval shot without turning a mattress into an overpriced long-term bill.
Why Mattress Financing Feels Harder With Bad Credit
A shopper in Eastern CT can walk in needing one simple fix. Replace the mattress, break the cost into payments, and stop losing sleep.
Then the approval screen turns it into a credit problem.
Lenders are pricing risk, not your need
A mattress may be necessary for your back, your workday, and your household. The financing company still treats many of these applications like unsecured credit. The question is basic: how likely is this account to get paid back on time?
That is why the process feels cold. A denial does not mean the mattress is too expensive for its value. It usually means the lender sees recent late payments, high balances, thin credit history, or too much existing debt and decides the risk is too high.
That also explains why bad-credit shoppers often get very different results from different financing paths. A standard store credit line can be stricter. A promotional plan may still require stronger credit. A lease-to-own option may approve more easily, but the total paid can climb fast. The problem is not just getting a yes. It is getting a yes on terms that do not turn a basic mattress into an expensive long-term bill.
Your credit profile can change the answer quickly
One card balance can matter more than shoppers expect. High revolving balances can drag down approval odds even if income is steady, which is why it helps to understand utilization impact on credit score before you apply.
Timing matters here.
- If your cards are close to maxed out: a traditional revolving credit offer may be harder to get approved for.
- If you expect to shop more than one financing route: protect your score by understanding which applications use a hard pull and which start with a softer screening process.
- If you need the mattress right away: compare total repayment first, monthly payment second.
That last point is the one shoppers miss most. A lower monthly number can still cost far more overall, especially if the offer stretches payments out or adds fees.
Bad credit changes the type of offer, not just the odds
Shoppers with stronger credit usually get shown the cleanest offers first. Shoppers with damaged credit often get routed toward plans built around higher lender protection. That can mean deferred-interest promotions with strict payoff deadlines, equal-payment plans with narrower approval windows, or lease-style agreements that are easier to enter but cost more in the end.
Those are not small differences. They are different approval paths with different price tags.
If you want a plain-English breakdown of realistic approval routes, this guide on where to finance furniture with bad credit is a solid place to start. It focuses on what shoppers need to compare: approval fit, payment structure, and total cost.
Bad-credit mattress financing feels harder because it is harder. The useful move is to stop judging offers by the monthly payment alone and start judging them by the full cost, the payoff rules, and the approval path behind them.
How Promotional Financing Actually Works
You see a mattress marked with a low monthly payment, and it looks manageable. Then the paperwork shows payoff deadlines, interest conditions, or extra fees that change the price fast.
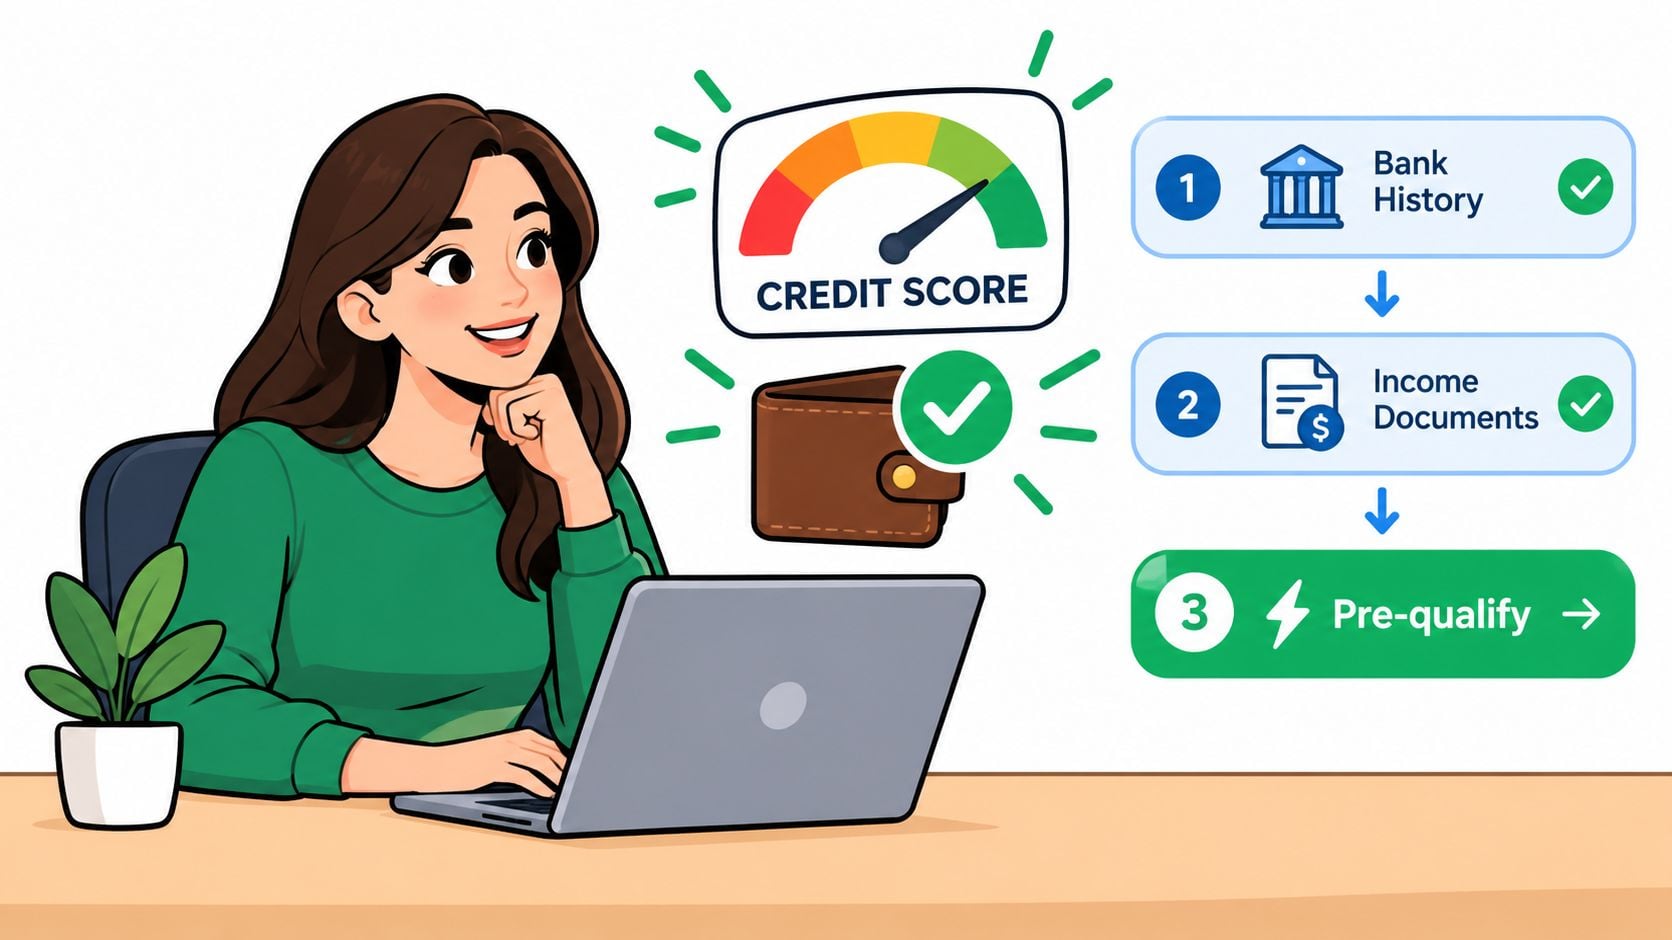
Promotional financing only makes sense if you read it as a total-cost deal first and a monthly-payment deal second. That matters even more for Eastern Connecticut shoppers with bad credit, because the offer you get may come with tighter rules or a more expensive backup if anything slips.
Equal monthly payments and deferred interest do different jobs
These offers get grouped together in casual conversation. They should not be.
Equal monthly payment financing sets a payment amount intended to retire the purchase within the promotional term. The structure is cleaner. If the payment amount pays off the balance by the deadline and you stay on schedule, the cost is easier to predict.
Deferred-interest financing gives you a deadline. Pay the full balance within that window and the promo can work out fine. Miss it, even by a small remaining balance, and the deal can get expensive in a hurry.
That is the key distinction. One structure is built around a payoff schedule. The other is built around a payoff condition.
The deadline matters more than the headline
“No interest” is the phrase shoppers remember. “If paid in full” is the phrase that decides the cost.
For buyers with bruised credit, that distinction matters because approval often comes with less room for error. A plan that looks cheap at checkout can turn into a costly mattress if the balance is still sitting there at the end of the promo period. Monthly payment alone will not tell you that.
Read the offer like this:
- What ends the promotion? A fixed payment schedule or a full payoff requirement.
- Will the listed payment clear the balance by the deadline? If not, you have work to do.
- What happens if you are late or short at the end? That answer changes the price.
- Are there extra charges beyond the mattress price? Fees and longer terms can erase the appeal of a small monthly number.
"Same as cash" needs plain reading
A lot of shoppers hear "same as cash" and assume it means low risk. It does not. It usually means the offer works well only if you follow the payoff rules exactly.
That is why a plain-English guide to 90 days same as cash furniture financing helps. That phrase sounds simple in ads, but the useful question is always the same: what do you pay in full if everything goes right, and what do you owe if it does not?
Use one simple test before you say yes
Take the full purchase price and compare it against the full amount you would repay under the offer, not just the monthly figure on the sign. Then match that number to your approval path.
If your credit is strong enough for a true promotional payoff structure, great. If your credit pushes you toward a stricter promo or a higher-cost alternative, know that before you sign. The smart move is not chasing the lowest monthly payment. The smart move is choosing the option you can finish at the lowest real cost.
Comparing Your Real Options for Bad Credit Mattress Financing
A shopper in Eastern CT sees a mattress at one monthly number in the ad, then gets to checkout and finds three very different paths. One asks for stronger credit but can stay close to the sticker price. One looks easy up front but punishes any balance left at the end. One approves more people because it leans on bank account history and income, then charges more over time.
That is the comparison.
Monthly payment matters, but total paid matters more. Approval path matters too. A plan you can get approved for today may still be the most expensive way to buy a mattress.
Mattress Financing Options Compared for Bad Credit Shoppers
| Financing Option | Approval Basis | Total Cost Risk | Best For |
|---|---|---|---|
| In-store promotional equal payments | Credit approval and ability to handle a fixed payment schedule | Lower, if the scheduled payments actually clear the balance within the promo term | Shoppers who can follow a set payoff plan and want the lowest real cost |
| Deferred-interest store financing | Credit approval plus strict compliance with promo terms | Moderate to high, because leftover balance can make the purchase much more expensive | Buyers who already know how they will pay it off before the deadline |
| BNPL or soft-check checkout installment plan | Softer initial screening in many cases, with repayment tied to checkout terms | Moderate, depending on fees, payment rules, and what happens after a missed payment | Shoppers who want to test eligibility without starting with a hard credit route |
| Lease-to-own | Active checking account, steady income, and authorization for automatic withdrawals | High, because the full repayment often runs well above the cash price | Buyers who need a mattress now and cannot qualify for cleaner credit options |
| Co-signer or shared application path | Stronger household credit profile | Varies, but often improves access to lower-cost structures | Households with a trusted co-applicant and a clear repayment plan |
| Secured credit approach | Deposit-backed or collateral-supported account structure | More controlled than many high-cost alternatives, depending on terms | Shoppers rebuilding credit who can prepare before buying |
For households sorting through checkout plans, this guide to buy now pay later furniture options gives a clearer picture of where that type of financing fits.
What each option really costs in plain English
Promotional equal payments are usually the best deal if you qualify and the math works. You get a set schedule, and if those payments retire the full balance on time, your mattress can cost close to the listed price.
Deferred-interest offers need more caution. They can work fine for a disciplined buyer with a clear payoff date. They can also turn a decent deal into an expensive one if even a small balance remains at the end.
Soft-check installment plans sit in the middle. Approval can be easier, which helps shoppers protecting their credit file or recovering from past credit trouble. But easier approval does not make the plan cheap. Read the fee structure, late-payment terms, and final repayment total before you say yes.
Lease-to-own is the access option. It exists for shoppers who need the mattress now and cannot get approved for traditional promotional credit. Treat it that way. If you use it, compare the full lease cost to the mattress price before signing anything. The gap can be large.
The blunt recommendation
Start with the option that gives you the lowest total repayment you can realistically finish. For many bad-credit shoppers, that means checking for a soft-screening installment path first, then comparing it against any in-store promotional offer you can qualify for.
Use lease-to-own only if cleaner options are not available and the need is immediate.
One federal review of buy now, pay later lending noted that checkout installment use expanded quickly as it became a common part of retail purchasing, which explains why more shoppers now see these offers at checkout (report on buy now, pay later market growth). More choices at checkout help with access. They do not lower the actual price on their own.
Here is the rule I would follow in the showroom. Pick the offer you can complete at the lowest full cost, not the one with the smallest monthly number.
How to Improve Your Approval Odds Before You Apply
You find a mattress that feels right, then the financing screen asks for income, bank details, and consent to a credit check. That is the worst time to get organized. Do the prep first, while you still have room to choose the cheapest path.
Start with the parts lenders actually check
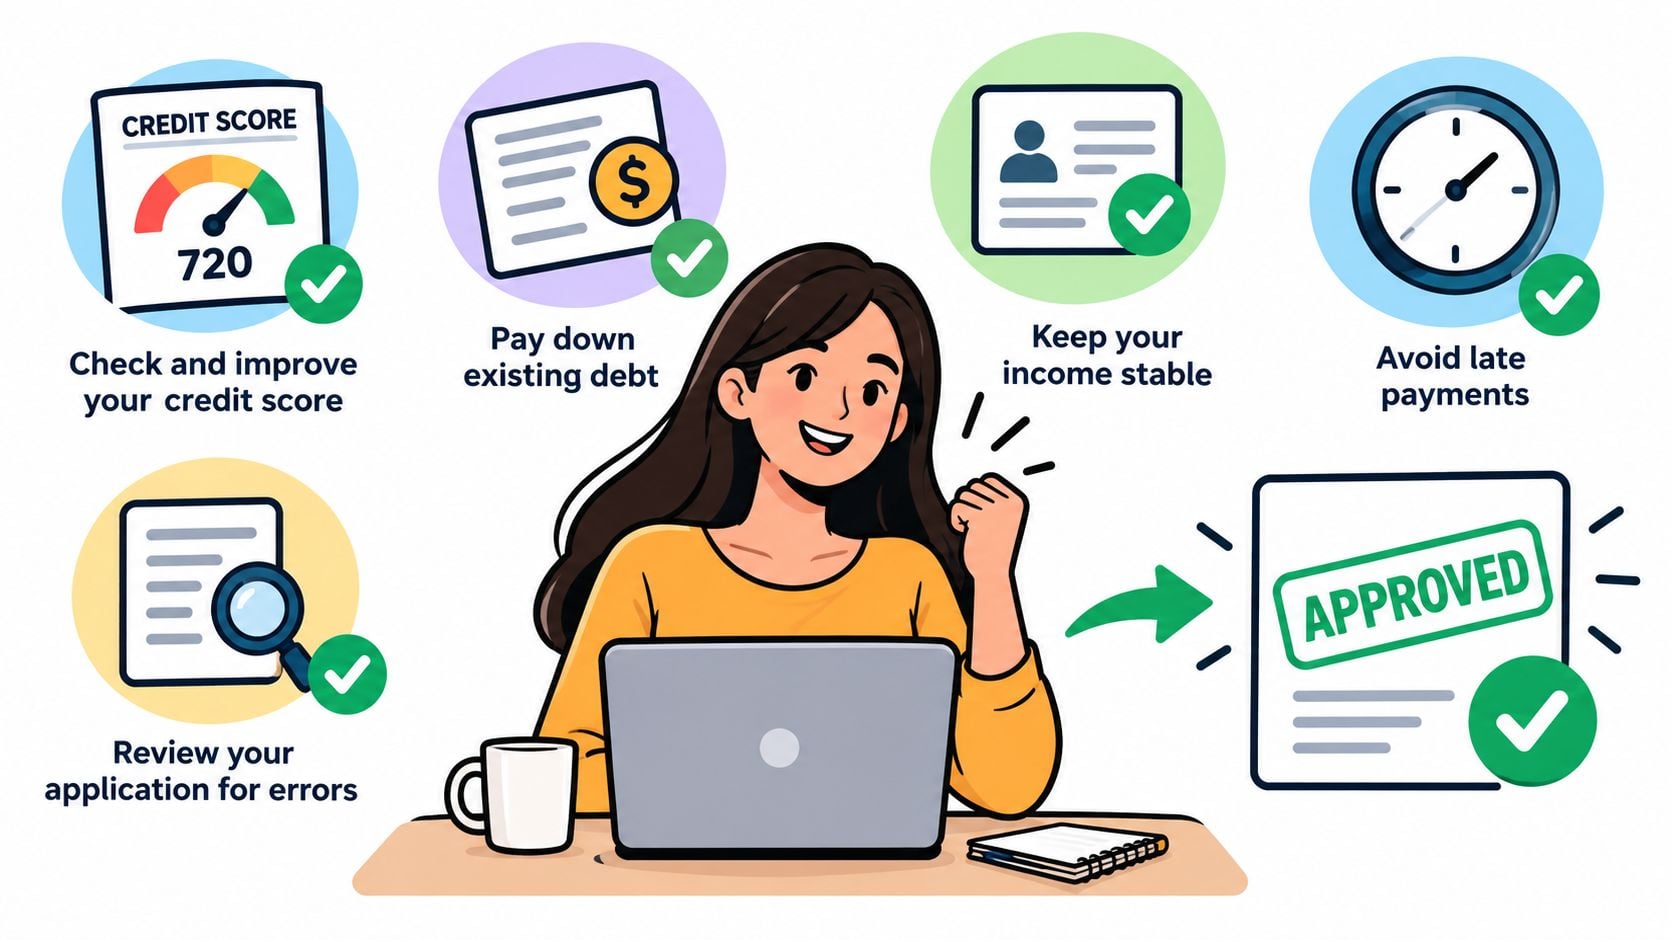
For many bad-credit mattress financing programs, approval depends on more than a score. Lenders and lease providers often look for steady income, an active checking account, and a recent history without bounced payments. If your account has been hit with overdrafts, fix that before you apply. A shaky bank account can sink an application even when the monthly payment looks manageable on paper.
Get your documents ready in one place. Keep recent pay stubs, benefit statements, or other proof of income easy to upload. Then slow down and apply with intention.
A practical checklist:
- Keep the checking account clean. Avoid overdrafts, returned payments, and account changes right before applying.
- Line up proof of income. Missing documents cause delays and denials.
- Start with soft-screening if available. That gives you a read on your options without adding unnecessary hard inquiries.
- Apply selectively. One focused application beats three rushed ones.
If you want a plain-English checklist before submitting anything, review ways to improve your approval odds.
Approval is only half the job
A yes does not mean the deal is smart. It only means someone found a way to approve you.
That matters with bad-credit mattress financing because the expensive option often looks easier at checkout. Higher-interest installment offers, repeated payment attempts tied to autopay, and lease structures can all turn a manageable purchase into a costly one. Independent lending data has shown bad-credit personal-loan rates can run high enough to make a mattress cost far more than expected over time.
Here is the standard I recommend. Judge every offer by total repayment first, payment schedule second, and approval speed last.
Use a cleaner process
Eastern CT shoppers usually do better when they decide the budget before they revisit the mattress options. Pick the maximum total amount your household can repay without strain. Then match that number to the mattress category you need, not the one that sounds good under showroom pressure or late-night checkout pressure.
After that, compare the financing path that fits your file. If score protection matters, start with the option that gives you a preliminary answer without a hard inquiry. If autopay is required, make sure the withdrawal date lines up with when money hits your account. That one detail causes more trouble than people expect.
Before you sign anything, read this guide on whether to finance a mattress. It helps sort out whether financing solves the problem or just spreads out a price that is still too high.
Finding Flexible Financing at Gorins Furniture and Mattress
Eastern CT shoppers don't need more financing jargon. They need a clearer buying experience, a realistic payment path, and a chance to test mattresses by feel before choosing a plan.
The local advantage is clarity
Since 1936, this family-owned, locally operated showroom has served Norwich and surrounding communities with a low-pressure approach built around Quality, Value, and Helpful Service. For mattress shoppers, that matters because sleep products aren't interchangeable. A buyer needs to know whether the mattress supports the body before taking on any payment obligation.
In the Sleep Gallery, shoppers can compare Tempur-Pedic, Serta, and Beautyrest in person, which is still the smartest way to evaluate comfort by feel and shop for healthier sleep. That showroom process is often more useful than reading endless online descriptions that don't answer whether a mattress feels supportive after five minutes lying on it.
Financing should support the purchase, not distort it
For shoppers who qualify, Gorins financing options include promotional financing through the Nest Credit Card and TD Bank partnerships, including equal monthly payment programs and no-interest-if-paid-in-full plans, subject to credit approval. That matters because those two structures can serve very different buyers.
A disciplined shopper can use equal monthly payments for cleaner budgeting. A buyer with irregular cash flow may need to be more cautious with deferred-interest timing. The value is in matching the structure to the household, not in forcing every shopper into the same script.
For households exploring broader poor-credit borrowing categories before stepping into a showroom, this breakdown to compare flex loans poor credit can help sharpen the total-cost questions to ask.
The purchase can be tailored beyond the mattress
The financing conversation also sits inside a bigger home-planning picture. Some households are replacing a mattress now and furnishing the rest of the room or home over time. That's where Gorins' broader custom programs matter, including Canadel Custom Dining with thousands of combinations and the F9 Custom Sofa series that lets shoppers tailor seating details to their lifestyle.
Other trusted categories in the showroom, including Flexsteel and Best Home Furnishings, reinforce the same idea. Buy with intention. Finance with intention too.
A mattress purchase works better when the shopper matches comfort, timing, and repayment in one decision instead of treating them as separate problems.
The after-purchase side matters as well. Local delivery, service support, and a 5-Star Delivery experience reduce the friction that often follows a major purchase, especially for busy families in Norwich, New London, Plainfield, Waterford, and nearby Rhode Island communities.
Your Next Steps to Better Sleep on Any Budget
A bad-credit financing situation doesn't need a miracle. It needs discipline. The smartest shoppers stop chasing approval language and start measuring total repayment, payoff conditions, and fit with actual income timing.
A short decision checklist
Before saying yes to any mattress financing offer, check these points:
- Total cost first: What will the mattress cost by the end, not just this month?
- Promo terms second: Is it equal monthly payments or deferred interest?
- Approval type third: Does the application use a soft check first, or does it go straight to a hard inquiry?
- Autopay reality: Will the payment date line up with income, every single month?
- Exit risk: What happens if one payment is late or the promo deadline is missed?
The strongest approach for most shoppers
For households with damaged credit, the cleanest path is usually the one that protects credit shopping, keeps the repayment window understandable, and avoids stretching the mattress into a costly long-term obligation. That often means saying no to a “cheap” monthly payment that hides an expensive structure.
Norwich-area buyers should also keep the product decision grounded. The mattress still has to solve the sleep problem. A bargain that doesn't support the body isn't value. An investment-grade mattress with a repayment plan that the household can finish is the better choice.
Since 1936, Gorins Furniture & Mattress has helped Norwich and Eastern CT families create homes they love. From custom-designed Canadel dining sets to the latest in Tempur-Pedic sleep technology, the showroom combines a massive selection with the personalized care only a local, family-owned business can provide. Visit the Norwich showroom, take the online Style Quiz, or browse the Clearance section for value-driven savings.
Gorins Furniture & Mattress gives Eastern CT shoppers a practical way to test mattresses by feel, compare promotional financing structures, and choose a payment path that fits real life. Neighbors in Norwich can visit the showroom for guidance, explore healthier sleep options from trusted brands, and shop with the support of a local family business that's been serving the community since 1936.